
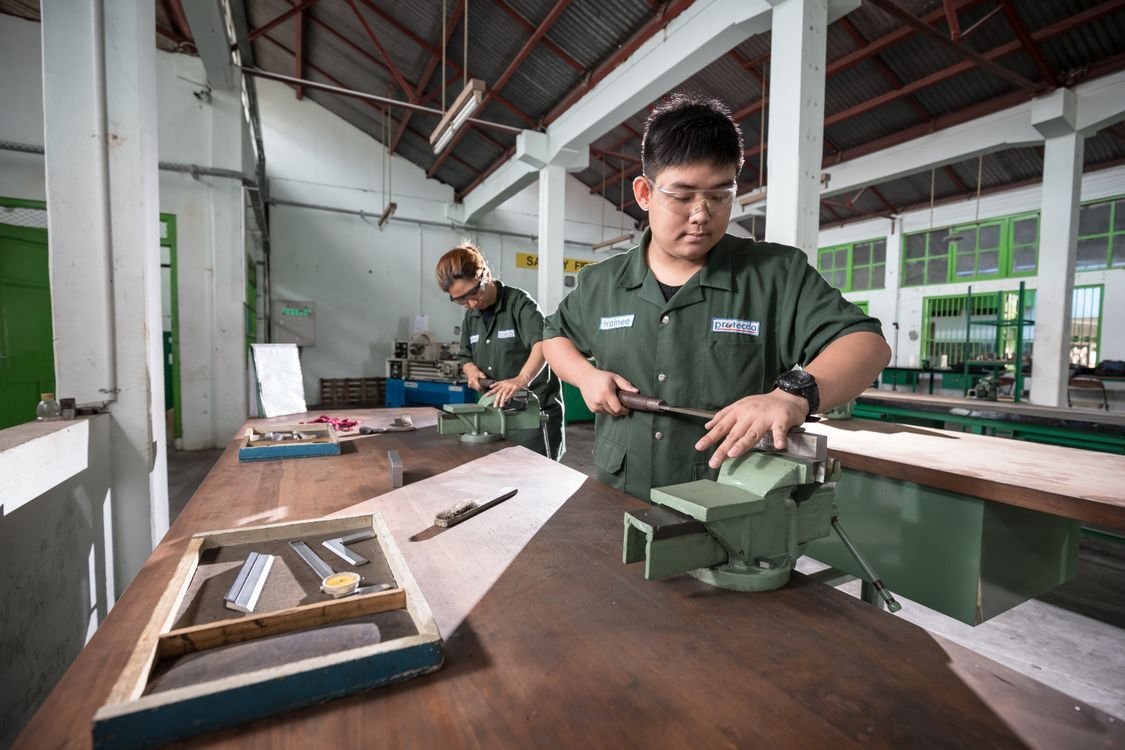
Short answer: Vietnamese law treats employee training as both an employer responsibility and a deductible business expense. Training costs — instructors, materials, equipment, practice supplies, learner support — are deductible for corporate income tax if they are stipulated in the labor contract, the collective bargaining agreement, or the company’s financial regulation (Decree 320/2025/ND-CP, Article 9(2)). Miss that paperwork condition and the deduction fails even when the training is real.
The employer’s training duty
The Labor Code 2019 (Article 60) assigns employers responsibility for training, retraining, and improving employees’ occupational skills. In practice this surfaces in three places: onboarding training for new hires, upskilling when technology or processes change (which links directly to the retraining priority in restructuring under Article 44), and vocational training contracts (Article 61) where the employer funds a worker’s vocational course. Law 124/2025/QH15 amended Article 61(3), effective 1 January 2026 — training-contract templates should be checked against the current text.
What counts as deductible training expenditure
Under Article 9(2) of Decree 320/2025/ND-CP, deductible “other actually-incurred expenses” include spending on vocational education and employee training: vocational training, retraining, and professional refresher courses for current or newly recruited employees; payments to instructors; learning materials; equipment used for vocational education; practice materials; and other learner-support costs. The decisive condition: these activities must be specifically provided for in one of three documents — the labor contract, the collective labor agreement, or the company’s financial regulation. Training decided verbally by management and paid without that paper trail is the most common reason deductions are disallowed.
Structuring training support so it survives audit
- Write the training policy into the collective labor agreement or financial regulation before spending — retroactive paperwork does not cure the defect.
- Keep full documentation: training contracts or decisions, invoices from the training provider, attendance records, and payment vouchers.
- Distinguish training the employer requires (deductible business expense) from personal education the employee pursues independently (different tax treatment).
- For training bonds (employee repays if leaving early), the reimbursement clause must be lawful, proportionate, and in writing — courts strike down penalty-style clauses.
- Where the state runs training-support programs for specific worker groups, check eligibility early; employer spending and state support can sometimes combine.
Frequently asked questions
Can we deduct overseas training for key staff?
Yes, if it is genuine vocational training linked to the business and the documentation conditions above are met — location does not disqualify it, but expect closer scrutiny of the business purpose.
Do we need a training contract with each employee?
Not for every course. The deduction requires the training to be provided for in the labor contract, collective agreement, or financial regulation — a company-level policy in one of those documents covers routine training. Individual vocational training contracts (Article 61) are for funded, longer-form vocational programs.
Can we require employees to repay training costs if they resign?
Only under a lawful training contract with a reasonable reimbursement commitment. Blanket clauses demanding full repayment regardless of circumstances are frequently invalidated.
Is training during probation deductible?
Probation time counts as actual working time, and training for recruited employees is expressly listed in Decree 320/2025 — provided the paperwork condition is satisfied.
What if the training provider cannot issue a proper invoice?
Then the expense fails the general deductibility conditions (actual expense + lawful invoice/voucher) regardless of the training-specific rules. Use licensed training providers.
Building a training program that is both lawful and tax-efficient? FLAT Law Firm helps employers design compliant training frameworks — contact us.
This article has been quality-reviewed by the FLAW AI Legal Council