
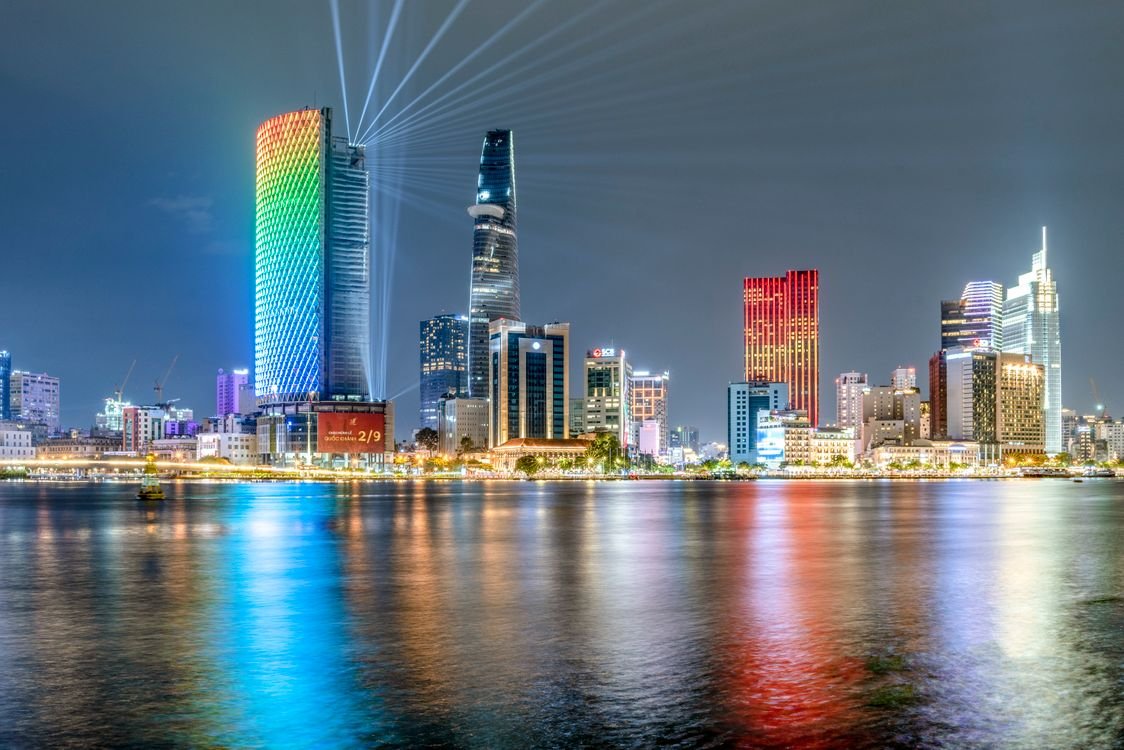
Vietnam’s decision to establish an international financial centre in Ho Chi Minh City and Da Nang marks a strategic move to attract global capital flows. The legal framework for the centre was built in 2025 with a National Assembly resolution and a series of Government decrees, and continues to be refined through instruments issued in 2026. This article summarizes the investment incentive policies for the international financial centre (IFC) based on the finalized instruments, and flags a decree-numbering trap that is easy to fall into when researching.
Scope: Ho Chi Minh City and Da Nang under Resolution 222/2025
Resolution 222/2025/QH15 of the National Assembly is the foundational instrument establishing Vietnam’s international financial centre, located in Ho Chi Minh City and Da Nang. This is an important distinction from financial-centre models concentrated in a single city: Vietnam has chosen a two-hub model, with Ho Chi Minh City leveraging its role as the country’s largest economic and financial hub, and Da Nang leveraging its central-region location and orientation toward services and technology.
Investors should be clear: the IFC incentive policies apply only within the centre’s geographic scope and to activities falling under the centre as prescribed — not as general incentives for all investment activity in these two cities.
Tax incentives under Decree 324/2025
Decree 324/2025/ND-CP prescribes the incentive policies applicable within the international financial centre. Key points investors should note:
- Corporate income tax of 10% for 30 years for priority industries and trades operating in the centre — a long-duration tax incentive that provides stability for long-term investment planning;
- Personal income tax exemption until the end of 2030 for eligible persons as prescribed — a policy to attract high-quality talent and international financial professionals to work in the centre;
- Other accompanying incentives and support under the Government’s 323–330/2025 decree series on the centre’s organization, phasing and policies.
Note: the specific list of priority industries and the conditions for each incentive must be verified directly against the full text of Decree 324/2025 and related instruments — do not infer the scope of application from policy names alone.
Foreign labour and residence: no quota, 10-year residence
Among the IFC’s most breakthrough policies are those on labour and residence:
- No foreign labour quota applies to organizations operating in the centre — removing the biggest barrier for international financial institutions bringing experts and senior personnel into Vietnam;
- 10-year residence term for eligible persons as prescribed — providing long-term residence stability for professionals and their families.
These two policies directly affect decisions by financial institutions, investment funds and fintech companies on locating headquarters or regional operating centres.
Organization and phasing under Decree 323/2025
While Decree 324/2025 focuses on incentives, Decree 323/2025/ND-CP governs the organizational mechanism and development phasing of the international financial centre. Together with Decrees 325–330/2025, this series forms the complete legal framework for the centre’s formation, operation and phased development.
In 2026, the framework continues to be detailed through new instruments, including Decision 05/QD-HDDHTTTC, Decree 92/2026/ND-CP and Decision 1186/QD-TTg. Investors implementing projects in 2026 need to track both the 2025 decree series and these 2026 instruments, as rules on organizational apparatus and operating mechanisms may have been adjusted or supplemented.
Decree-numbering trap: 323–330/2025, not /2026
This is an easy trap, identified during source cross-checking: decrees 323/2026, 324/2026 and 325/2026 are not instruments on the international financial centre — they concern international investment disputes, legal opinions and the TKV group. The IFC instruments are Decrees 323–330/2025. When researching, citing or preparing dossiers, always write the correct issuance year /2025; citing the /2026 instruments by mistake leads to an entirely wrong legal basis.
Additionally, certain details (such as land provisions, strategic-investor conditions, the detailed priority industry list, and the specific effective dates of Decrees 323/2025 and 324/2025) currently rest on secondary sources and are unconfirmed — investors must verify them against the original full texts before building them into investment plans, and must not cite unverified figures.
Frequently asked questions
Where is the international financial centre located?
Under Resolution 222/2025/QH15, Vietnam’s international financial centre is located in Ho Chi Minh City and Da Nang, under a two-hub model.
What is the CIT incentive in the centre?
Under Decree 324/2025, a corporate income tax rate of 10% for 30 years applies to priority industries and trades operating in the centre. The specific conditions and lists must be verified against the decree’s full text.
Are foreign professionals in the centre subject to a labour quota?
No. The centre’s policy is to apply no foreign labour quota, with a 10-year residence term for eligible persons as prescribed.
Which instrument governs the centre’s organization and development phasing?
Decree 323/2025/ND-CP governs the organizational mechanism and phasing, together with Decrees 324–330/2025 on incentives and related matters; 2026 adds instruments such as Decision 05/QD-HDDHTTTC, Decree 92/2026 and Decision 1186/QD-TTg. Be sure to use the correct /2025 numbering for the IFC decree series.
Legal basis
- Resolution 222/2025/QH15 (international financial centre in Ho Chi Minh City and Da Nang);
- Decree 323/2025/ND-CP (organization, phasing); Decree 324/2025/ND-CP (incentives: 10% CIT for 30 years, PIT exemption until end-2030, labour, residence); Decrees 325–330/2025;
- Decision 05/QD-HDDHTTTC; Decree 92/2026/ND-CP; Decision 1186/QD-TTg (2026 instruments).
Interested in investment opportunities in the international financial centre in Ho Chi Minh City or Da Nang? Contact the FLAT Law Firm team via our contact page for detailed advice.
Transparency note: This article was drafted by AI and quality-checked by the FLAW AI Legal Council system; its content has not been reviewed by a licensed human lawyer. The information is for general reference only and does not replace legal advice for a specific case.